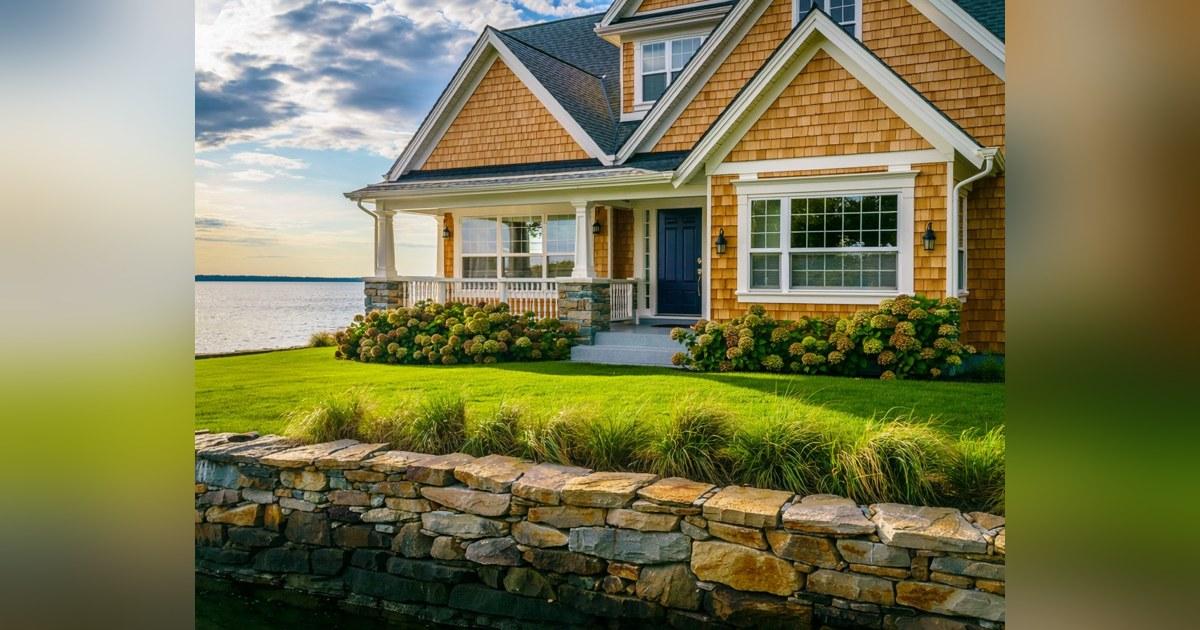
Connecticut has expanded the flood risk section of its residential property condition disclosure under Public Act 25-33, a change that directly affects homeowners along the Fairfield County shoreline. Buyers now expect clear answers about flood zones, flood history, and insurance before they make an offer, according to Kristin Egmont, a Coldwell Banker Realty agent licensed in Connecticut since 2003.
“Transparency is what really needs to start before the home is listed,” Egmont said. “Not after the buyer has the contract.” For sellers in sought-after waterfront communities such as Westport, Fairfield, Norwalk, including Rowayton, and Darien, the law shifts the timing of flood disclosure from a mid-transaction formality to a pre-listing imperative.
The implications for sellers are significant. A buyer who learns about flood zone status, prior flooding, water intrusion, insurance costs, and lender requirements early can plan around them. A buyer who learns them halfway through the transaction often comes back to renegotiate or walks away. Egmont says the disclosure works best when it gives buyers enough information to make a real decision, not just a checked box on a form. “Buyers also have to think about it,” she said. “They need to understand elevation, drainage, what the insurance premium is going to be, and what kind of financing requirements their lender is going to require if they have financing.”
For sellers, Egmont advises stating the facts plainly: “Let them know, this is in a flood zone, you’re going to need flood insurance, my current policy costs me this a year.” That level of transparency, she says, fits into a broader principle: the issues a seller deals with before going to market are the ones that won’t derail the deal later. “The more we address these items before listing a property, the fewer surprises we’re going to have during the negotiations,” she said.
The law’s impact extends beyond flood disclosure. Egmont notes that a common misconception among sellers is that listing is a single step—take photos, put the home online, and the market will do the rest. Instead, she spends time with sellers before listing to walk the property, identify improvements that make financial sense, plan staging, and flag potential inspection issues. For some homes, a pre-inspection can be worth considering so problems are found and addressed on the seller’s timeline rather than the buyer’s.
For coastal sellers planning to list in the coming months, Egmont’s advice is to gather information now: flood zone status, any history of flooding or water intrusion, current insurance costs, elevation information if it exists, and records of past claims. Having that in hand before the listing goes live gives buyers confidence and gives sellers more control over the negotiation. Sellers should also review the current disclosure requirements with a Connecticut real estate attorney, since the rules apply to the condition report they will sign. Answers to common seller questions are available on Egmont’s seller FAQs page.
The expanded disclosure law matters because it formalizes what coastal buyers have increasingly demanded: transparency about flood risk before commitment. For an industry navigating rising insurance costs and climate-related uncertainty, the change raises the bar for sellers and their agents, making pre-listing preparation a critical step rather than an optional one. As Egmont puts it, addressing these items early is the best way to avoid surprises at the negotiating table—a lesson that now carries legal weight in Connecticut.