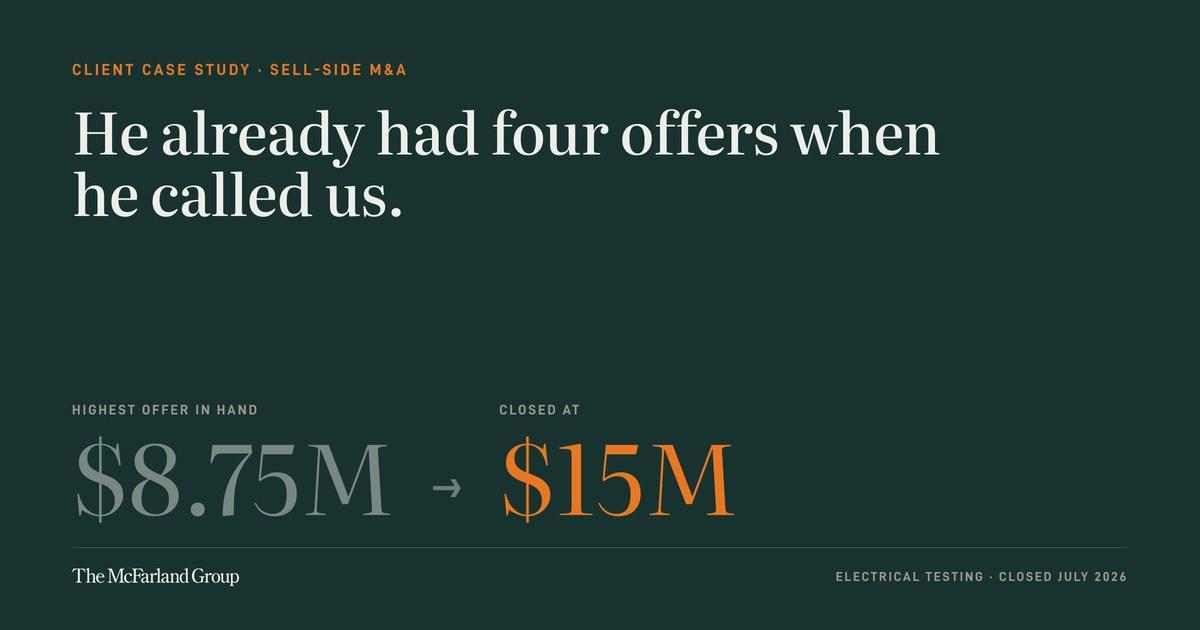
The McFarland Group has published a case study of a sell-side engagement that closed in July 2026, involving a founder-owned electrical testing and field services company that the owner had run for twenty years. When the owner approached the firm, he already held four signed letters of intent, with the highest offer at $8.75 million. The transaction ultimately closed at $15 million, with no escrow and a working capital formula unchanged from the one the firm proposed at the outset. The owner continues to lead the business.
The case study is written for owners who find themselves in a similar position: offers arrive before an advisor does, and the owner must decide whether a formal process is worth running when buyers are already at the door. Rather than replacing the buyers the owner had been speaking with, The McFarland Group ran a competitive process around them. All four remained at the table, joined by three additional qualified parties, with every participant working from identical information on the same deadline. The buyer the owner selected had been in his original group, though the terms were not the ones originally on the table.
Because the owner intended to stay on and roll equity, the engagement also weighed fit alongside economics: growth plans, capital appetite, how much autonomy he would hold after closing, and how each buyer’s existing operators described being owned by them. He elected to roll approximately ten percent of the proceeds.
The section of the case study the firm emphasizes first covers diligence. Reaching agreement took about six weeks, while reaching a closing took three more months. Four diligence teams worked through a twenty-year-old, founder-run company, and seven items surfaced that were live risks to the transaction. Several were news to the owner himself, including an employment matter from before the sale process, workforce documentation questions, and three separate threads on the integrity of the company’s S corporation election that carried seven-figure back tax exposure if any of them had broken. Each was worked through or cleared before closing.
“We could not promise him a number, and nobody honestly can,” said John Bruckner, Managing Partner of The McFarland Group. “What we could promise was a competitive field and the backing to get through the part that comes after the handshake. The months between signature and closing are where deals get retraded, and none of what we found was visible on the day he was close to signing by himself.”
The firm has anonymized the company, its owner, and all bidders at the client’s request. The full case study is available at themcfarlandgroup.com/case-study/sell-side-electrical-testing. The McFarland Group is an advisory firm based in Omaha, Nebraska, founded by Byron McFarland, and has guided over $3 billion in business value through more than 200 ownership transitions over two decades. More information is available at themcfarlandgroup.com.
For business owners, the case illustrates that accepting the highest early offer can leave significant value on the table. Running a competitive process—even with buyers already in hand—can materially improve terms, while thorough diligence is essential to uncover hidden liabilities that could derail a deal or reduce its value. The gap between signing and closing remains a critical period where retrading can occur, making expert guidance particularly valuable.